
By Chris Kobz, Founder, HappyDog
California public employees… a lot of you served before you ever put on a badge, a stethoscope or a teacher’s lanyard. Veterans Day was last Wednesday, so here’s one for you.
If you’re a veteran, you earned one of the strongest home loans out there. Here’s what a VA loan does, whether California sellers still shy away from it, and why it’s worth a look even if you’ve saved up a down payment.
What is a VA home loan?
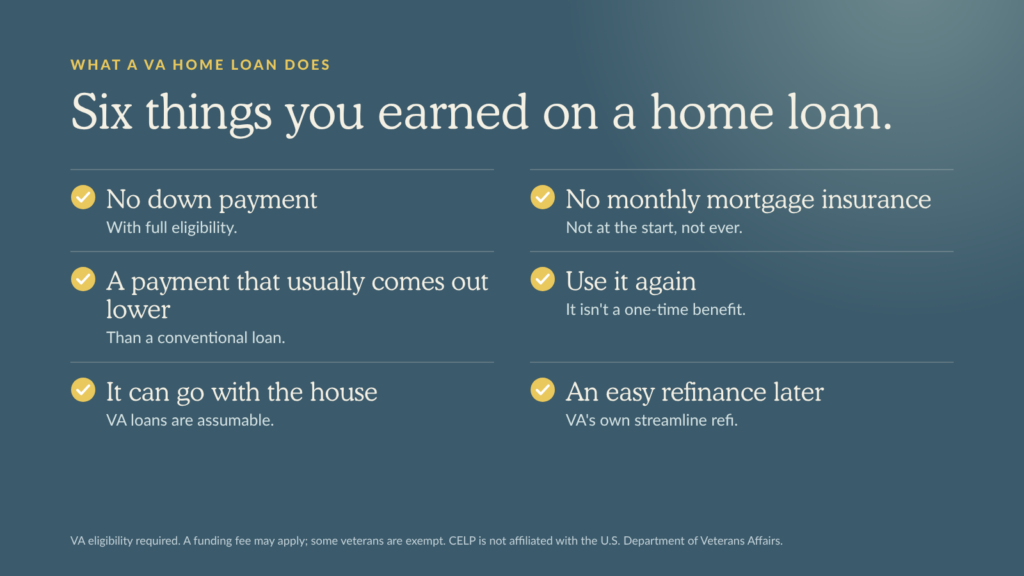
A VA loan is a home loan guaranteed by the U.S. Department of Veterans Affairs. You get it through a mortgage company like us, not from the VA directly. Here’s what it gets you:
- No down payment with full eligibility
- No monthly mortgage insurance, ever
- A payment that usually comes out lower than a conventional loan with the same down payment
- Reusable, so it isn’t a one-time benefit
- Assumable, so a future buyer may be able to take over your loan
- An easy streamline refinance down the road
Do California sellers accept VA loans?
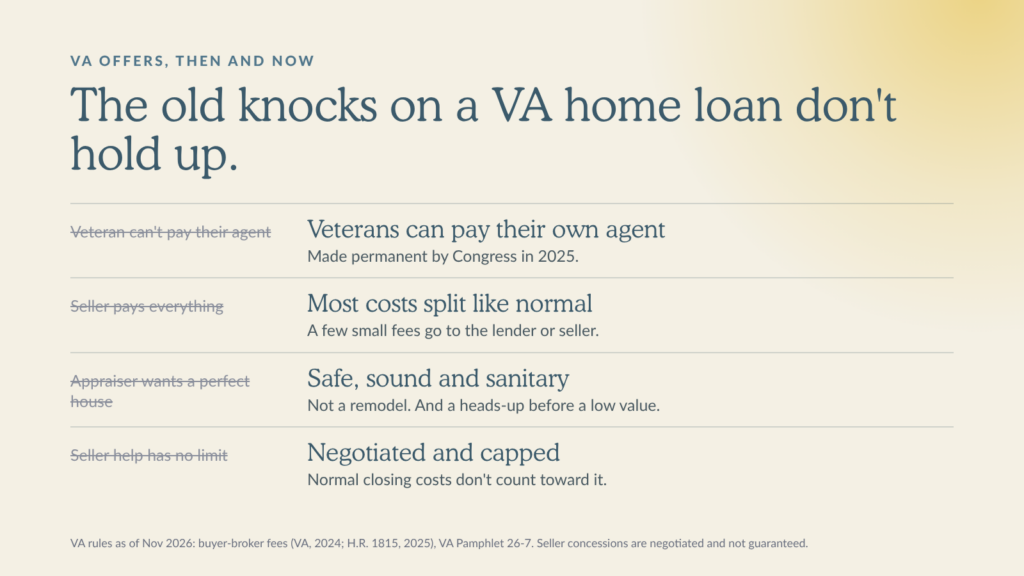
They should, and more of them do now. VA offers used to cost the seller more than a normal sale. That’s mostly gone.
- Veterans can pay their own buyer’s agent. VA lifted the old ban in 2024 and Congress made it permanent in 2025.
- Most closing costs split the way they normally would. A short list of small fees can’t be paid by the veteran, so the lender or seller covers those.
- The appraisal wants safe, sound and sanitary, not a remodel. If the value looks low, the appraiser has to warn the lender first so better comparable sales can be sent in.
- Seller concessions are capped at 4%, and normal closing costs don’t count toward that.
And this market helps. Home sales just hit their slowest pace in 16 years, homes are sitting about 51 days, and about 1 in 5 listings has had a price cut. A ready VA buyer gets a seller’s attention.
Should I use a VA loan if I have a down payment?
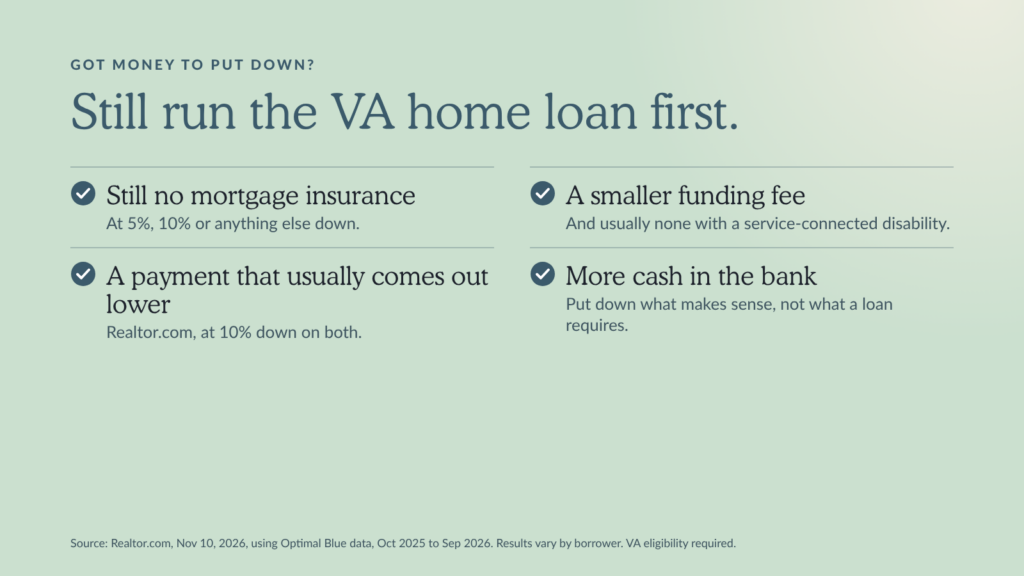
Run it before you rule it out. With 5% or 10% down you still never pay mortgage insurance, and the funding fee gets smaller. If you have a service-connected disability, there’s usually no funding fee at all.
Realtor.com compared the two this week on a median-priced home. With 10% down on both, the VA payment came out lower than conventional. That’s a real reason to look, even with savings in the bank.
Can I refinance a VA loan later?
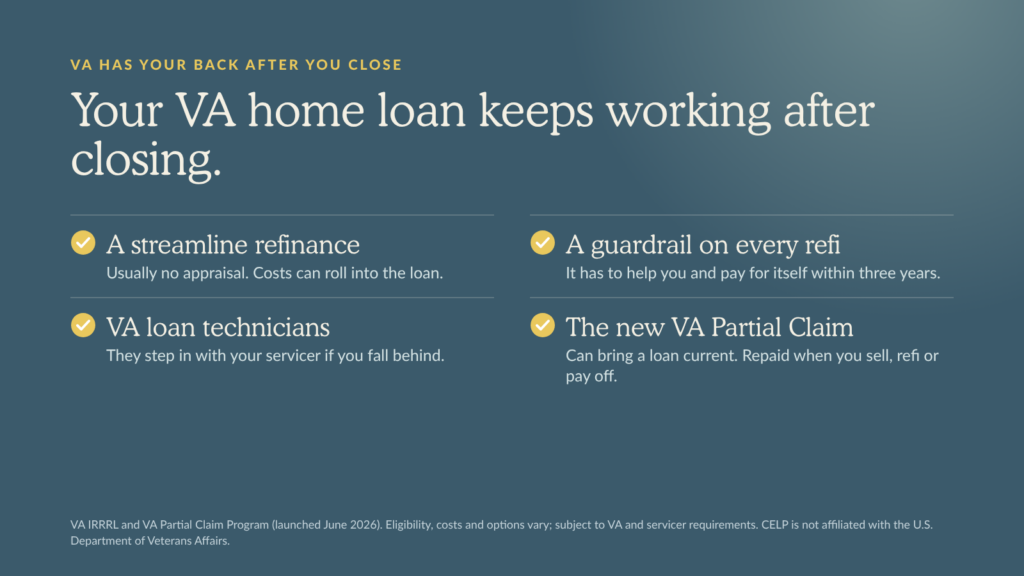
Yes, and it’s the easy part. VA’s streamline refinance, the Interest Rate Reduction Refinance Loan (IRRRL), usually needs no appraisal and no stack of income paperwork. Closing costs can roll into the new loan, so you typically don’t bring money to the table.
VA also built in a guardrail. The new loan has to clearly help you, and the costs have to pay for themselves within three years.
What happens if I fall behind on a VA loan?
VA doesn’t leave it all to the loan servicer. VA loan technicians can step in for you and work through repayment plans, forbearance or a modification. Life happens to everybody… that’s exactly what this is for.
And as of 2026, the new VA Partial Claim Program can pay the past-due amount after a three-month trial payment plan. You don’t pay it back until you sell, refinance or pay off the home.
What California public employees who served can do now
- Get pre-approved. OfferReady lines up your numbers so your offer is ready when you find the house.
- Compare VA and conventional side by side. We’ll show you both payments on our VA loans page and on a real quote.
- Know your payment. Run a few prices through the mortgage calculator before you fall for a house.
- Tell your agent you’re using VA up front. A good agent will know how to write a strong VA offer.
VA loan questions from California public employees
Can I use a VA loan and CELP together?
Yes. A VA loan is the loan type. CELP is how HappyDog prices loans for California public employees. If you’re eligible for VA, we’ll price your VA loan for you.
Is a VA loan only for first-time buyers?
No. It’s reusable. You can use it again on a later home.
Do I need a down payment on a VA loan?
Not with full eligibility. You can still put money down, and it lowers the funding fee.
Will a seller pick a conventional offer over my VA offer?
Some still might, out of habit. But the old reasons mostly don’t apply anymore, and in a slow market a ready buyer is a ready buyer.
We don’t discount. We start lower.
californiaemployeeloans.com A program of HappyDog
General information, not legal, tax or investment advice. VA program details are as of November 13, 2026 and can change. CELP is not affiliated with or endorsed by the U.S. Department of Veterans Affairs or any government agency. VA loans require a Certificate of Eligibility and are subject to VA and lender guidelines. A VA funding fee may apply; some veterans are exempt. Seller contributions are negotiated, not guaranteed, and subject to VA limits. IRRRL eligibility, costs and savings vary; closing costs added to the loan increase the amount financed. Loss mitigation and partial claim options are subject to VA and servicer requirements. Not all borrowers will qualify. This is not a commitment to lend. VA loans are guaranteed by the U.S. Department of Veterans Affairs. CELP pricing is offered by HappyDog; it is not a VA benefit or a government program.
California Employee Loan Program (CELP) is not a government program, a grant, or a government-backed loan. CELP is a mortgage pricing model operated by HappyDog, a registered DBA of Go Rascal Inc., a licensed mortgage broker. Loans are arranged through third-party lenders. NMLS ID 2072896 (nmlsconsumeraccess.org). All loans are subject to underwriting approval, terms and conditions may apply, and programs are subject to change without notice. We are an Equal Housing Opportunity mortgage broker. We do not discriminate based on race, color, religion, national origin, sex, familial status, or disability. This is intended for consumers in Arizona, California, Colorado, Florida, Illinois, Oregon, and Texas only. Go Rascal Inc. does not conduct business as HappyDog in any states not listed. THIS PRODUCT OR SERVICE HAS NOT BEEN APPROVED OR ENDORSED BY ANY GOVERNMENTAL AGENCY, AND THIS OFFER IS NOT BEING MADE BY AN AGENCY OF THE GOVERNMENT.
Sources
- U.S. Department of Veterans Affairs: VA Partial Claim Program (2026)
- U.S. Department of Veterans Affairs: Interest Rate Reduction Refinance Loan
- Realtor.com: VA loans can help veterans become homeowners about four years sooner (Nov 10, 2026)
- U.S. Department of Veterans Affairs: buyer-broker fee update (June 2024)
- Congress.gov: H.R. 1815, VA Home Loan Program Reform Act
- NAR: Existing-home sales, October 2026
- Redfin housing tracker, four weeks ending Nov 8, 2026