A 2-1 Buydown temporarily lowers your monthly payment on a fixed-rate mortgage. Your note rate stays fixed for the life of the loan, but for the first two years your payment is calculated using a rate 2 percentage points below your note rate in year one and 1 percentage point below it in year two. Funds set aside at closing cover the difference. Depending on the property and market, a seller may agree to concessions that can help pay for an eligible buydown.
How it Works
Your monthly payment steps up over the first two years, while your note rate stays the same for the life of the loan.
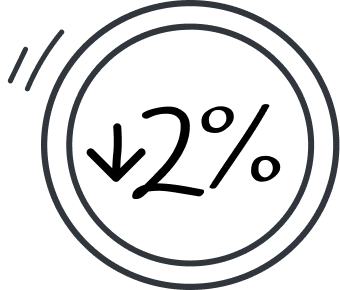
1st Year
Your payment is calculated at 2 percentage points below your note rate.
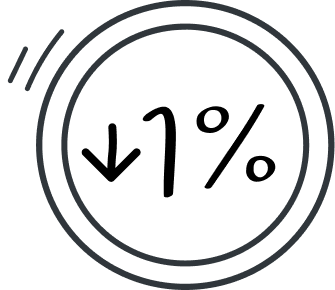
2nd Year
Your payment is calculated at 1 percentage point below your note rate.
3rd Year+
Your full monthly payment, based on your note rate, for the remaining loan term.
The buydown reduces principal and interest only. Property taxes, insurance and HOA dues are not reduced and may change. Your note rate, APR and payments for each period will be shown on your Loan Estimate.
A 2-1 Buydown can lower your monthly payment during your first two years of homeownership, when moving and setup costs tend to add up.
Lower Payments Up Front
Keep more room in your budget during the first two years, when moving costs, furniture and repairs add up.
Seller Concessions
Depending on the property and market, a seller may agree to concessions that can help cover the cost of an eligible buydown. Concession limits vary by loan program.
Plan Ahead
Your Loan Estimate shows your principal and interest payment for each stage of the buydown, so you can plan your budget before you close.
Time to adjust
Your payment increases gradually, giving you time to prepare for your full payment. Refinancing may be an option later, but it isn't guaranteed and depends on future rates, your equity, credit, income and lender approval.
Is a 2-1 Buydown Right for you?
A 2-1 Buydown may be worth discussing with a loan officer if you:
Want lower monthly payments during your first two years in a new home
Can comfortably afford the full payment that begins in year three
Are buying a home where the seller may be open to concessions
Want a fixed-rate mortgage with a temporary payment reduction
You’ll qualify based on your full payment at the note rate, not the reduced payment. Before choosing a buydown, review your full monthly payment, including property taxes, insurance and any HOA dues, to make sure it fits your budget. Our loan officers can walk you through whether a 2-1 Buydown makes sense for your situation.
We’re Here To Help
Work with one of our loan experts who will explore all your options. No pressure, just guidance.
No. It’s a fixed-rate mortgage, and your note rate stays the same for the life of the loan. The buydown temporarily reduces your monthly payment for the first two years.
Does a buydown cost anything?
Yes. The cost equals the total payment reduction over the two-year buydown period, and it’s paid at closing. A seller, builder or the buyer can pay it, depending on the purchase and loan program.
Do I qualify at the lower payment?
No. You qualify based on your full payment at the note rate. Your total payment can still change over time if property taxes, insurance or HOA dues change.
What happens if I refinance or sell before the two years are up?
How unused buydown funds are handled depends on the lender and loan program. Your loan officer can explain how this works for your loan.
Can I combine a 2-1 Buydown with other programs?
In some cases. Eligibility depends on your loan program and the guidelines of any assistance program. Talk to a loan officer about your options.
How do I ask the seller to pay for it?
Your real estate agent can include a request for seller concessions in your offer. Sellers aren’t required to agree, and concession limits depend on your loan type and down payment. We can help you understand how much may be allowed for your loan.
For any unanswered questions, reach out to our support team. We’ll respond as soon as possible to assist you.
A 2-1 Buydown is a temporary payment subsidy. The note rate is fixed for the life of the loan and does not change during the buydown period. The buydown applies to principal and interest only; property taxes, insurance and HOA dues are not reduced. Borrowers must qualify at the full note rate. Seller concessions are subject to negotiation and loan program limits. Refinancing is not guaranteed and depends on future rates, property value, credit, income and underwriting approval. All loans are subject to credit approval. Programs, terms and conditions are subject to change without notice.